Learning how to sell a house without a realtor in Kansas can save you a listing commission. It also hands you the pricing, marketing, showings, negotiations, and paperwork. From Wichita bungalows to rural acreage outside Topeka, a for-sale-by-owner (FSBO) sale starts with an honest read on what your home is worth and how much work you’re signing up for.
This guide walks through the Kansas steps in order. Prep the property, market it to qualified buyers, handle disclosures, and reach closing without surprises. You’ll also see the costs that stay on your side of the ledger no matter who lists the house, including buyer-agent compensation, title services, and repairs.
How to Sell a House Without a Realtor in Kansas: Is FSBO Right for You?
Learning how to sell a house without a realtor in Kansas starts with an honest look at the workload. FSBO, short for “for sale by owner,” suits owners with a well-priced property, time to run the process, and a plan for marketing, showings, negotiations, paperwork, and closing. It’s an easier call when a buyer is already in view. A relative, a neighbor, your tenant, or a cash buyer you’ve spoken with before. Sometimes that’s a company that buys houses in Topeka, KS.
Selling without a realtor doesn’t mean selling alone. Kansas FSBO sellers often hire a real estate attorney to read the purchase agreement and required disclosures. Most use a title company or closing agent to keep the sale on track. Many pay for photography, a yard sign, online listing exposure, or a pre-listing inspection. Kansas law exempts owners from the license requirement when selling their own property, under K.S.A. 58-3037. You still carry the legal and financial risk.
Control is the real benefit. You set the list price. You set the showing schedule, approve the marketing, and negotiate face-to-face with buyers. You may also reduce the commission expense associated with hiring full-service real estate agents. Savings aren’t automatic, though. A buyer with an agent may ask you to cover that agent’s commission, and an overpriced or poorly presented home can lose more in final sale price than any commission would have cost.
FSBO works best on a home in good condition, in a neighborhood where comparable sales are easy to read, with a seller who answers the phone. It gets harder with unusual homes, rural properties, inherited houses, homes needing repairs, or several owners who all have to agree. Sellers in the southeast corner of the state often call cash house buyers in Pittsburg, KS, rather than list a house that needs work. Kansas sellers also need accurate property-condition disclosures ready, plus patience to clear title, inspection, appraisal, or financing problems before closing.
Organized, comfortable talking about price, willing to pay a pro where it counts? FSBO gives you a direct path to a sale. Want the widest buyer reach and someone else holding the moving parts together? A realtor may earn the fee.
Calculate the True Cost of a Kansas FSBO Sale
Skipping a listing commission is the headline. The true cost of a Kansas FSBO sale sits underneath it. Start with the sale price you actually expect, then write down every dollar that leaves at closing. Plenty of sellers still offer compensation to a buyer agent, since homes listed by real estate brokers compete for the same buyers. That fee is negotiable. Put it in the calculator anyway, rather than treating it as an afterthought.
Closing costs come next. A Kansas seller’s share usually covers title charges, deed preparation, prorated property taxes, the payoff of an existing mortgage, and any repairs or buyer credits negotiated. One break helps here. The state charges no real estate transfer tax, and the legislature ended the mortgage registration fee in 2019. Recording a deed costs $21 for the first page and $17 for each additional page. County practice, contract terms, and lender requirements still vary, so ask a title company for an estimate early.
- Expected sale price
- Realtor commission, including buyer-agent compensation
- Expected closing costs and mortgage payoff
- Repairs, concessions, and buyer credits
- Marketing, photography, listing, and legal fee expenses
- Your time for showings, disclosures, offers, and inspection requests
Run the comparison honestly. Estimate your net proceeds from selling on your own, then estimate the net from a traditional listing. Subtract the same items from both: the realtor commission, a buyer-agent fee, expected closing costs, mortgage payoff, concessions, and any marketing, photography, listing, or legal fee. Then price your own hours, because a FSBO seller’s time is a real cost of the sale. Setting up showings, screening buyers, reading offers, handling disclosures, and answering inspection requests is a part-time job for weeks on end.
Buyers price risk into an offer when they sense nobody is coordinating the transaction. A few thousand dollars of difference in sale price can swallow the commission you saved, especially in a hot Kansas market where looks and exposure drive demand. Flip it around, though. A seller who knows the neighborhood cold, has the home ready, and has a straightforward buyer often does well without a realtor. No single path always costs less. Calculate the full transaction, use current local estimates, and judge each option by proceeds and certainty rather than by a single percentage of the sale price.
FSBO cost checklist
- Start with a realistic expected sale price, based on recent comparable home sales.
- Include any buyer-agent fee you plan to offer. It’s negotiable, but it affects buyer interest and exposure.
- Estimate seller closing costs, including title charges, deed preparation, prorated taxes, repairs, and negotiated buyer credits.
- Subtract your mortgage payoff, liens, and any outstanding property obligations from projected sale proceeds.
- Add direct FSBO expenses such as photos, marketing, listing fees, legal review, signage, and admin help.
- Compare net proceeds with those of a traditional listing, accounting for differences in sale price and concessions.
- Weigh a seller’s time, screening, disclosures, showings, inspections, and the certainty of reaching a closing.
Build, Price, and Launch Your Kansas Listing
A Kansas real estate sale begins with a listing that buyers can actually evaluate. Before home selling goes public, pull the property details together. Gather recent repair records, confirm square footage and features, and prepare clear photos showing condition, layout, and exterior. Settle on pricing supported by nearby sales, active competition, and your own location, condition, and updates. An accurate price draws stronger early attention than a listing that drops three times in six weeks.
Have seller disclosures, title documents, and other paperwork ready to hand over. Ready documents keep showings and offers moving. Decide how broadly to market the listing and who answers buyer questions, appointment requests, and feedback. For many owners, an MLS listing provided through a flat-fee service offers local MLS visibility while you retain control. That matters in active Kansas City markets, where sharp photos, a fair asking price, and fast replies decide which homes get seen first.
Prepare the House and Set a Defensible Asking Price
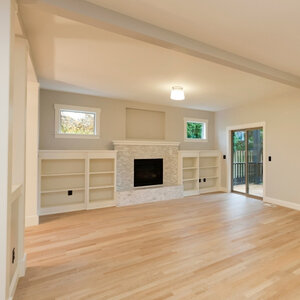
Treat the house like a buyer will inspect every surface, because the serious ones will. Handle obvious deferred maintenance. Clean hard, brighten the dark rooms, and clear enough personal items that a visitor can read the scale and function of each space. Photograph the property only after all of that is done. Small repairs aren’t always required, but anything unresolved should show up in both the presentation and the sale price.
- Clean thoroughly and brighten dark rooms.
- Address visible deferred maintenance.
- Remove personal items that obscure each room’s purpose or scale.
- Photograph the property only when it is orderly and well-lit.
Gather what a buyer, lender, or title company will ask for: utility details, repair invoices, survey records if available, warranties, permits, and any HOA materials. Get title documents reviewed early, while ownership questions, liens, easements, or payoff needs on the property are still easy to solve. Kansas sellers should also put together a thoughtful disclosure package. The state has no statewide mandated seller disclosure form for a private sale, but you still can’t hide or lie about a known material defect. Most owners here use a disclosure statement from a local real estate association anyway. Address water intrusion, roof history, mechanical problems, structural concerns, and past repairs honestly. When you’re unsure, keep the records and ask a lawyer instead of guessing.
Good pricing means looking past the highest asking price on your street. Compare homes that actually closed, matched on location, size, age, condition, and features, then look at what’s pending and what’s still sitting. A property near a Kansas City employment center can carry a premium that a similar home three miles away won’t. Adjust for updates, lot quality, school boundaries, and market momentum. You’re not after an aspirational number. You want a price a buyer can defend to a lender’s appraiser, one that earns qualified attention in the listing’s first days.
Pricing and preparation checklist
- Complete visible repairs, deep-clean every room, brighten dark spaces, and reduce personal items before showings.
- Take listing photos only after the home is orderly, staged for scale, and well-lit.
- Collect utility records, invoices, permits, warranties, surveys, and HOA papers.
- Review title materials early to identify liens, easements, ownership issues, or payoff requirements.
- Disclose known material conditions honestly, including water damage, roof history, mechanical issues, and structural repairs.
- Compare recent closed sales with similar homes, then look at active and pending local listings.
- Adjust the price based on location, updates, lot quality, school boundaries, condition, and current market momentum.
Market a FSBO Home Through MLS Exposure and Direct Outreach
FSBO sellers don’t have to choose between a quiet private marketing campaign and a full traditional brokerage relationship. A flat-fee MLS service places a home in the local multiple listing service for one upfront charge, which routes the listing into agent search tools and the portals buyers browse at night. Read the terms first. Check photo limits, listing duration, permitted edits, syndication, showing support, and how fast the provider forwards buyer-agent inquiries.
Build the MLS listing around facts buyers use to decide. Lead with what’s verifiable: an updated kitchen, a finished basement, a walkable setting, a newer roof, or an oversized garage. Then give accurate room counts, dimensions, property taxes, school information, and exclusions. Good photos, a clear floor plan, and honest remarks about the property beat hyped-up marketing every time. One rule changed recently. Since August 17, 2024, offers of buyer-agent compensation can’t appear anywhere in the MLS. If you plan to cover a buyer agent’s fee, negotiate it directly with that agent and put it in writing. Buyer concessions, such as help with a buyer’s closing costs, can still be advertised.
MLS exposure pairs well with direct outreach. Share the listing with neighbors, local contacts, and community groups that allow marketing posts. Build a simple property webpage or information sheet with photos, disclosures, financing details, and instructions for requesting a showing. Reply fast, confirm every appointment, and keep notes on each conversation. That same paper trail makes negotiation and contract review far easier later.
Handle Showings, Offers, and Negotiations Like a Seller
Once the home is on the market, a seller’s job shifts from preparation to disciplined decisions. Set a system for showings. Confirm appointments in writing, log who visited, put medications and valuables away, and leave before buyers arrive.
Decide ahead of time how you’ll communicate. Answer promptly, but keep conversations on access, property facts, and next steps. Buyers will ask why you’re selling, how low you’ll go, and whether anyone else has made an offer. Be honest without negotiating against yourself. Disclosure covers the home’s condition, not your reasons for moving. If a buyer works with a real estate agent, settle early whether you’ll pay that agent a commission, then put the agreement in writing.
An offer is more than its sale price. Read the whole purchase agreement: earnest money, financing type, inspection and appraisal contingencies, requested repairs, possession date, what personal property stays, and the closing timeline. A cash buyer takes mortgage and appraisal risk off the table, though proof of funds still matters. On a financed offer, a prequalification letter means little. A real mortgage preapproval, serious earnest money, and fair contingency periods can make a slightly lower offer the safer one.
Negotiate from the terms you actually need. Sellers who want certainty trade a price for fewer contingencies. Sellers who need time ask for a rent-back arrangement or a later closing. Make counteroffers specific and dated, and send them through the proper channel. Avoid side promises by text that contradict the written contract. With multiple buyers, treat every party fairly and never share one buyer’s private terms with another.
Before you sign, a local real estate attorney reading the purchase agreement and required disclosures is cheap insurance. An accepted offer isn’t the goal. A buyer and a contract that reach a clean closing are.
Kansas FSBO Paperwork, Disclosures, and Closing Steps
Paperwork decides a Kansas FSBO sale as much as the right buyer does. You aren’t legally required to hire a real estate agent or pay a real estate commission to sell your own home. You are on the hook for getting the documents, disclosures, and timing right. Start with a purchase agreement naming the property, price, earnest money, financing terms, inspection and appraisal contingencies, requested repairs, possession date, and who pays which closing costs. A vague contract can lead to costly arguments months after the offer is accepted, which is why many sellers have a real estate attorney review it first.
Pull your title documents together too: the prior deed, a survey or plat if you have one, mortgage payoff information, homeowners association materials, and records of major improvements or warranties. Kansas closings run through title companies rather than attorneys. The title company examines the chain of title, flags liens that must be cleared, prepares the deed, and transfers the funds. If a mortgage sits on the house, build lender payoff processing into the timeline.
Seller disclosures deserve the same care. Kansas doesn’t mandate a single statewide residential disclosure form for every private sale, but an “as is” label won’t protect you from hiding what you know. Write the disclosure out yourself: the roof, foundation, water intrusion, plumbing, electrical systems, septic or sewer service, environmental concerns, prior repairs, boundary questions, and any insurance claims or damage history. Federal law adds one more step for homes built before 1978. Give the buyer the EPA’s “Protect Your Family From Lead In Your Home” pamphlet, disclose known lead-based paint, and allow a 10-day window for a lead inspection. Buyers can waive that window. You still have to offer it.
Once inspections, financing, and title work are finished, closing pulls the documents together. Deed, settlement statement, the buyer’s loan paperwork, tax and utility prorations, and whatever affidavits the title provider wants. Read the final figures before signing so you understand your net proceeds and each closing cost line. Keep copies of everything after the sale, including the purchase agreement, disclosure forms, and closing statement.
Knowing how to sell a house without a realtor in Kansas doesn’t make it the right move for every seller. If the property needs repairs you’d rather not make, or you’d trade some sale price for a closing date you can count on, it’s worth comparing a cash offer against your FSBO estimate. Real Estate Rescue buys Kansas houses as-is, and you can contact us at (316) 925-7851 for a cash offer to set beside your own numbers. Run both numbers and keep whichever leaves you better off.
Frequently Asked Questions
Can I sell my house without a realtor in Kansas?
Yes. Kansas homeowners can sell their property without a real estate license or a listing commission. You’ll still price the home, market it, run showings, negotiate offers, give accurate disclosures, and finish the title and closing work.
Do I need an attorney to sell a house FSBO in Kansas?
An attorney isn’t required in Kansas, since title companies handle closings here. Having a real estate attorney review the purchase agreement and disclosures still reduces risk. Legal review earns its keep when the property has title issues, multiple owners, inherited ownership, or unusual contract terms.
What paperwork do I need to sell a house by owner in Kansas?
Typical documents include a purchase agreement, seller property-condition disclosures, a lead-based paint disclosure for homes built before 1978, deed information, mortgage payoff details, HOA documents, repair records, and closing forms. Your title company can name anything else the transaction needs.
Do Kansas FSBO sellers have to pay a buyer’s agent commission?
No. Buyer-agent compensation is negotiable, and since August 2024, it can’t be advertised in the MLS at all. Offering it may still help attract buyers who have agents. Include any proposed buyer-agent fee in your selling costs before you set a price.
What closing costs does a Kansas home seller usually pay?
Seller costs can include mortgage payoff, prorated property taxes, title-related fees, deed preparation, agreed repairs or credits, a buyer-agent commission, and marketing or legal expenses. Kansas charges no transfer tax, which helps. Everything else varies by county, contract terms, and lender requirements, so request an early title estimate.
Helpful Kansas Blog Articles